 Seenclassified
 Request Access
Construction Financing Explained: Funding Real Estate Projects From the Ground Up
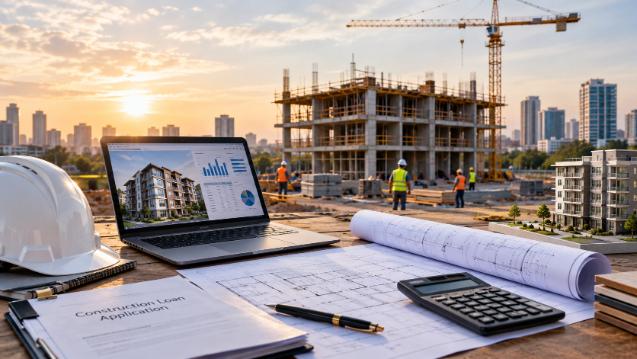
Construction financing is an important part of real estate development. Whether someone wants to build a single-family home, a small apartment building, or a large commercial property, construction requires money at every stage. Investors need funds to purchase land, hire contractors, buy materials, pay workers, obtain permits, and complete the project.
Unlike a traditional mortgage, which usually helps someone purchase an existing property, construction financing is designed to pay for a building project as the work progresses. The money may be released in stages instead of being provided all at once.
Understanding how construction financing works can help property investors plan their budgets, choose suitable funding options, and reduce financial risks. In this guide, we will explain the main types of construction financing, how lenders evaluate projects, and what investors should know before starting construction.
What Is Construction Financing?
Construction financing is money borrowed or raised to pay for building a new property or completing a major development project. It can cover different expenses, including land preparation, building materials, labor, equipment, and contractor payments.
For example, an investor may purchase an empty piece of land and plan to build a six-unit apartment building. The project may require money for architectural designs, permits, construction work, plumbing, electrical systems, and interior finishes.
Instead of paying every expense from personal savings, the investor may use a construction loan or another funding arrangement.
The funding method depends on the size of the project, the investor's financial position, the expected completion date, and the property's future use.
Construction financing is commonly used for:
-
New residential homes
-
Apartment buildings and multifamily properties
-
Office buildings
-
Retail stores and shopping centers
-
Industrial buildings and warehouses
-
Mixed-use developments
-
Major property redevelopment projects
Each project has different funding needs. A small residential construction project may qualify for a different loan than a large commercial development.
How Does Construction Financing Work?
Construction financing generally follows a planned process. The lender or funding provider reviews the project before approving the money. Once approved, the funds are often released in stages as construction reaches specific milestones.
Here is how the process commonly works.
1. Create a Construction Plan
Before applying for funding, the investor needs a clear plan. This plan should explain what will be built, how much it will cost, and how long the work is expected to take.
The investor may need architectural drawings, contractor estimates, a construction schedule, and information about the land.
For a commercial project, the plan may also include expected rental income, operating expenses, and an estimate of the property's value after completion.
A clear plan helps the investor understand the total funding requirement before work begins.
2. Calculate the Total Project Cost
Construction costs include more than the price of materials and labor. Investors must also consider permits, inspections, insurance, professional fees, utility connections, and other expenses.
It is also important to include a contingency budget. This is extra money reserved for unexpected costs, such as material price increases or necessary design changes.
For example, if a project is expected to cost $500,000, the investor should not assume that the construction work will always stay within that amount. A reasonable contingency allowance can help protect the project if expenses increase.
The appropriate reserve depends on the property's condition, project complexity, local market, and advice from qualified construction professionals.
3. Apply for Financing
After preparing the plan and budget, the investor can approach banks, credit unions, specialized lenders, or private funding providers.
The lender will review the borrower's credit history, available cash, existing debts, construction experience, and ability to repay the loan.
The lender may also evaluate the property, contractor, construction budget, and expected value after completion.
For commercial development, lenders often examine the project's expected income and the demand for similar properties in the area.
4. Receive Funds in Stages
Many construction loans use a process called a draw schedule. Under this arrangement, the lender releases money at agreed stages rather than providing the entire loan amount at the beginning.
For example, funds may be released after the foundation is completed, when the building structure is finished, and when major systems or interior work reach specific milestones.
The lender or an appointed inspector may check the progress before approving each payment.
This process helps the lender confirm that the money is being used for the project. It also means investors must plan carefully because contractors still need to be paid on time.
5. Complete the Project and Repay the Loan
Once construction is complete, the investor must follow the loan agreement to repay or replace the financing.
Some construction loans are short-term and require repayment when the project is finished. Other arrangements allow the borrower to convert the construction loan into a longer-term mortgage, if the loan terms and lender permit it.
Investors may also repay the loan by selling the completed property or arranging permanent financing.
The best exit strategy should be considered before construction begins, not after the building is finished.
Main Types of Construction Financing
There is no single funding option that works for every real estate project. Investors should compare different financing methods based on cost, repayment terms, project size, and risk.
1. Construction-Only Loans
A construction-only loan provides money specifically for the building phase. It is usually designed for a limited period and may release funds in stages as construction progresses.
After the project is complete, the borrower generally needs to repay the loan, sell the property, or arrange another financing option.
For example, a developer may use a construction-only loan to build a small apartment property and then obtain a commercial mortgage once the building is ready for tenants.
This approach can provide flexibility, but it creates refinancing risk. If interest rates rise or the lender's requirements change, replacing the loan may become more expensive or difficult than expected.
2. Construction-to-Permanent Loans
A construction-to-permanent loan combines construction funding with long-term mortgage financing under one arrangement.
During the building phase, the loan provides money for construction. Once the project meets the lender's completion and conversion requirements, the financing changes to a permanent mortgage.
This option may reduce the need to arrange an entirely separate mortgage after construction. Depending on the loan structure, it may also reduce the number of separate closing processes.
However, not every property or borrower qualifies. Investors should review conversion requirements, interest rates, fees, and repayment terms before signing the agreement.
3. Commercial Construction Loans
Commercial construction loans are used to build income-producing properties, such as office buildings, shopping centers, warehouses, hotels, and apartment complexes.
Lenders may evaluate the project's expected rental income, the borrower's experience, the construction budget, and the expected value of the completed property.
For larger developments, the lender may also review market research, pre-leasing agreements, tenant demand, and the developer's financial resources.
These loans can support significant projects, but approval requirements may be more detailed than those for smaller residential construction.
4. Owner-Builder Financing
Owner-builder financing may be available to people who want to manage construction themselves instead of hiring a general contractor to oversee the entire project.
This approach can give experienced builders more control over scheduling and expenses. However, lenders may consider owner-builder projects riskier because managing construction requires time, knowledge, and coordination.
The borrower may need to demonstrate relevant experience, provide detailed cost estimates, and show that the project can be completed safely and professionally.
Availability depends on the lender and local regulations.
5. Private Construction Financing
Private lenders may provide funding for projects that do not fit traditional bank lending requirements.
For example, a developer may need short-term financing to purchase land, begin construction, or complete a project before selling it.
Private financing can sometimes offer faster decisions or more flexible terms. However, it may also involve higher interest rates, additional fees, shorter repayment periods, or stricter default conditions.
Investors should compare the full borrowing cost rather than choosing a loan based only on how quickly the money is available.
6. Equity Partnerships
Not every construction project must be financed entirely with borrowed money. An investor can also work with a partner who contributes capital in exchange for a share of the project's profits or ownership.
For example, one partner may provide the land and manage the development, while another contributes cash toward construction costs.
This arrangement can reduce the amount of debt required, but it also means sharing decision-making authority and potential profits.
The partners should establish their responsibilities, ownership percentages, funding commitments, and exit terms in a written agreement prepared with appropriate professional advice.
How Much Money Can an Investor Borrow?
The amount available for construction depends on several factors. Lenders do not usually approve a loan based only on the borrower's requested amount.
They may consider the total project cost, the property's expected completed value, the borrower's available equity, and the ability to repay the debt.
Two common measures are loan-to-cost and loan-to-value.
Loan-to-Cost (LTC)
Loan-to-cost compares the loan amount with the total eligible project cost.
For example, suppose a construction project has a total cost of $600,000, and the lender agrees to finance 75% of that amount.
The calculation would be:
Loan amount = $600,000 × 75% = $450,000
The investor would need to cover the remaining $150,000, along with any expenses that are not covered by the loan.
This is a simplified example. Actual loan-to-cost limits and eligible expenses vary by lender and project.
Loan-to-Value (LTV)
Loan-to-value compares the loan amount with the property's appraised value. For construction financing, a lender may also consider the estimated value of the completed property.
For example, if a completed building is expected to be worth $800,000 and the proposed loan is $480,000, the loan-to-value ratio is 60%.
The lender may use this figure alongside other measures to determine the project's risk.
A higher expected property value does not automatically guarantee approval. The lender must still consider the construction budget, borrower qualifications, market conditions, and repayment plan.
Example: Financing a Small Apartment Construction Project
Imagine an investor plans to build a small apartment building with eight rental units.
The estimated project budget is:
-
Land purchase: $150,000
-
Construction and labor: $400,000
-
Permits, professional fees, and other costs: $50,000
-
Total estimated project cost: $600,000
The investor has $150,000 available and wants to finance the remaining $450,000.
In this simplified example, the requested loan would cover 75% of the estimated project cost.
Before approving the loan, a lender might review the land value, construction contract, building plans, expected rental income, and the investor's financial position.
The investor should also estimate future expenses such as property management, maintenance, insurance, taxes, utilities, and vacancy.
Suppose the building is expected to generate $96,000 in annual rental income when fully occupied. That does not mean the investor will keep the entire amount as profit. Operating expenses and loan payments must be considered before calculating the project's potential return.
If construction costs increase or the property takes longer than expected to attract tenants, the investor may need additional cash.
This example shows why a realistic budget and a clear repayment plan are essential before construction begins.
What Do Lenders Look for When Approving Construction Financing?
Lenders want to understand whether the project is realistic and whether the borrower can meet the loan obligations.
Several factors may influence their decision.
Credit History and Financial Strength
Lenders may review the borrower's credit history, income, outstanding debts, cash reserves, and previous repayment behavior.
A stronger financial profile can improve the chances of qualifying for suitable terms, although approval also depends on the project and the lender's requirements.
Construction Experience
Experience can be especially important for commercial or complex developments. A borrower who has completed similar projects may be better prepared to manage contractors, budgets, permits, and delays.
First-time developers may need a qualified construction team or an experienced project manager to strengthen their application.
Detailed Budget and Timeline
Lenders generally expect a clear estimate of project expenses and a realistic construction schedule.
The budget should identify major costs and include an allowance for unexpected expenses. The timeline should account for permits, inspections, material delivery, and other possible delays.
An incomplete budget can create problems after construction begins.
Property Value and Market Demand
The lender may review the location, expected completed value, local property prices, and demand for similar buildings.
For rental properties, the lender may also evaluate expected rents, vacancy assumptions, and operating costs.
A property in a market with weak demand may present more risk than a similar project in a stronger rental market.
Repayment or Exit Strategy
The borrower should explain how the loan will be repaid.
Possible strategies include refinancing into a long-term mortgage, selling the completed property, or using other available funds.
The strategy should be realistic and should include a backup plan if construction takes longer or the market changes.
Common Costs Associated With Construction Financing
The total cost of financing includes more than interest. Investors should understand every major charge before accepting a loan offer.
Common costs may include:
-
Interest charged on borrowed funds
-
Loan origination or arrangement fees
-
Property appraisal and inspection fees
-
Legal and documentation costs
-
Surveying and valuation expenses
-
Draw administration fees
-
Extension fees if the project exceeds the agreed loan period
-
Costs associated with refinancing or early repayment, where applicable
Some construction loans charge interest only on the amount that has been drawn, while other arrangements may calculate charges differently. Investors should check the exact loan agreement.
It is also important to understand when interest payments begin and whether any fees must be paid before construction starts.
Comparing the total expected borrowing cost can help investors avoid choosing a loan that appears affordable at first but becomes expensive over time.
Risks of Construction Financing
Construction projects can create attractive opportunities, but they also involve risks that investors should understand.
Construction Delays
Bad weather, permit issues, labor shortages, and material delivery problems can delay completion.
A delay may increase interest expenses, extend contractor costs, and postpone rental income or a planned sale.
Investors should use a realistic timeline and maintain enough reserves to manage reasonable delays.
Cost Overruns
Materials, labor, and equipment may cost more than originally expected. Design changes or unexpected site conditions can also increase expenses.
Detailed contractor estimates, clear contracts, regular budget reviews, and contingency funds can help control this risk.
Interest Rate Changes
Some construction loans have variable interest rates. If rates increase, borrowing costs may rise.
Investors should understand whether the rate is fixed or variable and estimate how higher payments could affect the project.
Market Changes
Property prices and rental demand can change during construction. A building may be worth less than expected when completed, or rental income may be lower than the original forecast.
Investors should use realistic assumptions rather than relying entirely on optimistic market predictions.
Refinancing Problems
Borrowers who plan to replace a short-term construction loan with a permanent mortgage may face difficulties if their financial position changes or the lender's requirements are not met.
It is wise to understand refinancing conditions early and consider alternative repayment options.
Contractor and Quality Issues
Poor workmanship, disputes, or contractor failure can delay completion and increase costs.
Investors should check contractor qualifications, verify references, use clear written contracts, and arrange appropriate inspections throughout the project.
How to Reduce Construction Financing Risks
Good planning cannot remove every risk, but it can help investors make better decisions.
First, obtain detailed estimates from qualified professionals before applying for financing. Make sure the budget includes both direct construction expenses and indirect costs.
Second, compare loan offers from more than one suitable lender. Review interest rates, fees, draw schedules, repayment dates, and default conditions.
Third, maintain a contingency reserve. Avoid committing every available dollar to the initial budget because unexpected expenses may arise.
Fourth, monitor construction progress and spending regularly. Compare actual expenses with the approved budget and investigate differences before they become serious.
Finally, prepare a realistic exit strategy. If the plan depends on refinancing or selling the property, consider what will happen if the market changes or the project takes longer than expected.
Working with experienced contractors, architects, accountants, and legal professionals can also help investors identify problems before they become expensive.
Is Construction Financing Right for New Real Estate Investors?
Construction financing can be useful for new investors, but building a property is often more complicated than purchasing an existing one.
A new investor must understand construction budgets, project management, permits, contractor agreements, financing terms, and the local property market.
Starting with a smaller project may make it easier to learn how these elements work together. Another option is to partner with an experienced developer or invest in a project managed by qualified professionals.
Before borrowing money, beginners should calculate the full project cost, identify the required cash contribution, estimate ongoing expenses, and understand the repayment deadline.
It is also important to avoid assuming that a completed property will immediately produce enough income to cover every expense.
Investors should proceed only when the project makes financial sense under realistic assumptions and they understand the risks involved.
Final Thoughts
Construction financing helps real estate investors fund projects from the planning stage through completion. It can support residential homes, apartment buildings, commercial developments, and other property projects that require substantial upfront investment.
The right financing option depends on the project's size, the borrower's financial strength, the expected completion date, and the plan for repaying the loan.
Construction-only loans, construction-to-permanent financing, commercial loans, private funding, and equity partnerships each offer different advantages and limitations.
Before starting a project, investors should prepare a detailed budget, compare financing terms, maintain a reserve for unexpected expenses, and develop a realistic exit strategy.
Successful construction investing requires more than obtaining money. Careful planning, responsible borrowing, experienced project management, and regular financial monitoring can help investors make informed decisions and manage the challenges of building real estate from the ground up.
Disclaimer: This article is for educational and informational purposes only. Construction financing terms, costs, and eligibility requirements vary by lender, property type, and location. Consult qualified financial, legal, tax, and construction professionals before making investment or borrowing decisions.
Invest in Luxury
Access curated opportunities across luxury assets, private markets, and alternative investments designed for long-term value creation and portfolio diversification.
Explore Opportunities
Private Cannabis Investing
The global cannabis market is expected to grow rapidly in the coming years. With this growth, investing with TheSeattleCannabis can be a smart move for those looking to diversify their portfolio. .
View Opportunities
 English
 Arabic
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek