 Seenclassified
 Request Access
Multifamily Real Estate Financing: A Guide to Apartment and Multi-Unit Investments
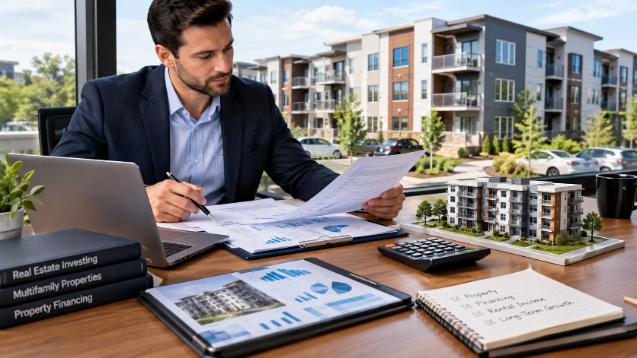
Multifamily real estate investing is a popular strategy for people who want to earn rental income and build long-term wealth through property. Instead of buying a single house for one tenant, investors can purchase apartment buildings or residential properties that contain several separate rental units.
However, buying a multifamily property can require a large amount of money. Investors may need funds for the purchase, repairs, property improvements, closing costs, and future maintenance. This is where multifamily real estate financing becomes important.
Understanding how financing works can help investors compare loan options, estimate their costs, and choose properties that fit their financial goals. It can also help them prepare for challenges such as vacancies, changing interest rates, and unexpected repairs.
In this guide, we will explain multifamily real estate financing, the common loan options available, how lenders evaluate apartment investments, and what investors should consider before purchasing a multi-unit property.
What Is Multifamily Real Estate Financing?
Multifamily real estate financing refers to the funding used to purchase, refinance, renovate, or develop residential properties containing multiple separate housing units.
These properties can range from a duplex with two apartments to a large apartment complex containing dozens or hundreds of units.
For example, an investor might purchase a four-unit building and rent each apartment to a different household. Another investor may acquire a larger apartment property and hire a professional management company to handle tenants, maintenance, and rent collection.
Financing for these investments may come from banks, credit unions, mortgage lenders, private lenders, or investment partners. The available options depend on the property's size, location, financial performance, and the investor's qualifications.
The financing process may also differ according to local lending laws and whether the property is treated as residential or commercial real estate.
Why Investors Choose Multifamily Properties
Multifamily properties offer several features that attract real estate investors. However, the benefits depend on the purchase price, rental demand, expenses, and quality of management.
1. Multiple Rental Income Sources
One important advantage is that a multifamily building can generate rent from several tenants.
Imagine an apartment building with eight units. If one tenant moves out, the remaining seven units may continue generating income while the owner searches for a replacement tenant.
This does not eliminate the risk of vacancies, but it can reduce dependence on a single tenant compared with owning one rental house.
Investors still need to account for unpaid rent, maintenance, tenant turnover, and the possibility that several units may become vacant at the same time.
2. Potential for Long-Term Appreciation
Property values may increase over time because of local development, population growth, improved transport links, or stronger housing demand.
However, appreciation is never guaranteed. Property prices can remain flat or decline because of economic conditions, rising interest rates, oversupply, or changes in the local rental market.
Investors should evaluate a property's current financial performance instead of relying entirely on the expectation that its value will rise.
3. Opportunities to Improve Property Performance
Some multifamily properties have opportunities for improvement. An investor might renovate outdated kitchens, repair common areas, improve lighting, or introduce more efficient maintenance systems.
These changes may help attract tenants or reduce operating costs. In some cases, improvements can support higher rents, provided the local market can justify them.
Before beginning renovation work, investors should estimate the costs and compare them with the potential financial benefits.
4. Potential for Portfolio Growth
Investors who successfully manage one multifamily property may eventually consider acquiring another.
Rental income, additional savings, and future financing may help support further purchases. However, lenders usually evaluate each transaction based on its own requirements, and existing debt can limit borrowing capacity.
Growing a property portfolio requires careful financial planning rather than simply purchasing as many units as possible.
Common Types of Multifamily Properties
Understanding the type of property you want to purchase is an important part of choosing the right financing strategy.
Duplexes, Triplexes, and Fourplexes
These smaller properties contain two, three, or four separate residential units.
They may appeal to first-time investors because the purchase price and management responsibilities can be more manageable than those of a large apartment complex.
Depending on the country, loan program, property use, and occupancy arrangements, some smaller multifamily properties may qualify for residential mortgage financing.
An owner who lives in one unit and rents out the others may have different financing options from an investor who plans to rent every unit.
Small Apartment Buildings
Small apartment buildings may contain several units and often require more formal management than a duplex or triplex.
Investors need to consider rental income, maintenance expenses, building insurance, local regulations, and the condition of shared areas.
Financing requirements can vary according to the number of units, the borrower's financial position, and the lender's policies.
Large Apartment Complexes
Large apartment complexes often operate more like businesses than individual rental homes.
They may require professional property management, regular maintenance planning, detailed financial reporting, and larger amounts of investment capital.
Financing may depend heavily on the property's income, expenses, occupancy, and ability to support debt payments.
Mixed-Use Residential Properties
Some buildings combine apartments with retail stores, offices, or other commercial spaces.
These properties can have several income sources, but their financing and management may be more complex. Investors should understand the lease arrangements, permitted uses, and risks associated with each part of the building.
Main Financing Options for Multifamily Investments
There is no single loan that suits every multifamily investment. The best option depends on the property's size, the investor's finances, and the purpose of the purchase.
1. Conventional Residential Mortgages
Conventional residential mortgages may be available for eligible smaller multifamily properties, depending on local rules and lender requirements.
The lender may review the borrower's credit history, income, existing debts, down payment, and property details.
Some programs may have different requirements when the borrower intends to live in one unit rather than rent out the entire building.
Investors should confirm whether a particular mortgage permits the intended rental use and whether any occupancy conditions apply.
2. Commercial Multifamily Loans
Commercial multifamily loans are commonly used for apartment buildings that are treated as commercial real estate for financing purposes.
Unlike some residential mortgages, these loans may place significant emphasis on the property's income and operating performance.
A lender may review current rents, occupancy, operating expenses, lease records, property condition, and the borrower's experience.
Loan terms, repayment periods, interest rates, and required equity contributions vary by lender and transaction.
Commercial financing may be suitable for investors purchasing larger apartment buildings or properties operated primarily as rental businesses.
3. Government-Backed Financing Programs
Some countries offer government-backed mortgage or housing finance programs that may support eligible multifamily purchases or development projects.
The rules depend on the specific program. Requirements may cover the property type, number of units, borrower eligibility, occupancy, affordability, and permitted use.
Investors should check official program information to confirm whether a particular property qualifies. Government-backed financing should never be assumed to be available for every apartment investment.
4. Portfolio Loans
A portfolio loan is generally a loan that a lender keeps in its own investment portfolio instead of selling through the usual secondary mortgage market channels.
Some lenders offer portfolio financing to borrowers with multiple properties or investment arrangements that do not fit their standard lending criteria.
The lender may consider the borrower's overall financial position, property holdings, rental income, and repayment ability.
Terms and eligibility vary, so investors should compare the full loan agreement with other available options.
5. Bridge Loans
Bridge loans provide short-term financing for specific situations.
For example, an investor may purchase an apartment building that needs substantial repairs before it can qualify for longer-term financing.
The investor may use short-term funding to complete approved improvements, stabilize occupancy, and then explore refinancing.
However, bridge loans can carry higher costs and shorter repayment deadlines. The investor needs a realistic exit strategy and should not assume refinancing will automatically be approved.
6. Private Lending and Investment Partnerships
Private lenders may provide funding for multifamily transactions based on the property, collateral, borrower, and proposed repayment plan.
Alternatively, investors may partner with individuals or companies that contribute equity in exchange for an ownership interest or a share of future profits.
Partnerships can help spread the financial burden, but they also introduce shared decision-making and potential disagreements.
A written agreement should explain capital contributions, ownership rights, responsibilities, distributions, additional funding requirements, and procedures for resolving disputes.
How Much Money Do You Need to Buy a Multifamily Property?
The amount required depends on the property's price, the financing terms, closing costs, repairs, and the cash reserves needed after the purchase.
Investors should calculate the total cash requirement rather than focusing only on the down payment.
Consider a hypothetical apartment building priced at $800,000.
Suppose a lender is willing to finance 75% of the purchase price. The estimated loan would be $600,000, leaving the investor responsible for $200,000 of the purchase price.
The investor may also need money for:
-
Closing costs and legal fees.
-
Property inspections and valuation.
-
Immediate repairs and maintenance.
-
Insurance and applicable taxes.
-
Initial management and leasing expenses.
-
Emergency reserves for vacancies and unexpected costs.
These expenses can add significantly to the amount required to complete the investment.
The example is illustrative only. Actual loan-to-value limits and financing requirements vary by lender, borrower, property, and jurisdiction.
How Lenders Evaluate Multifamily Properties
Lenders want to understand whether the borrower and the property can support the proposed financing. Several factors commonly influence their decisions.
Credit History and Financial Position
Lenders may review credit reports, income, existing liabilities, available savings, and the borrower's financial history.
Investors may also need to demonstrate that they have enough money to cover the required contribution and maintain reserves after closing.
Strong financial records can help lenders evaluate the application, but they do not guarantee approval.
Loan-to-Value Ratio
The loan-to-value ratio, or LTV, compares the loan amount with the property's accepted value.
For example, if an apartment building is valued at $800,000 and the proposed loan is $600,000, the LTV is 75%.
The remaining 25% represents the difference between the property's value and the loan amount. It does not include other purchase costs.
A lender may use the appraised value, purchase price, or another method specified in its lending policy.
Debt Service Coverage Ratio
The debt service coverage ratio, or DSCR, measures how much net operating income a property generates compared with its annual debt payments.
For example, suppose an apartment building generates $150,000 in annual net operating income and has $120,000 in annual debt service.
The DSCR is calculated as:
$150,000 ÷ $120,000 = 1.25.
This means the property's net operating income is 1.25 times its annual debt service.
Lenders may have minimum DSCR requirements, but the exact threshold depends on the financing arrangement. Investors should also test whether the property can support payments if rent falls or expenses rise.
Rental Income and Occupancy
The lender may review current rent rolls, lease agreements, vacancy levels, payment history, and local rental market conditions.
A rent roll lists the units, tenants, and rent amounts associated with a property.
Investors should verify the information instead of relying only on figures supplied in a sales listing. Advertised rents may differ from actual collected income, and some units may require repairs before they can be rented.
Property Condition and Location
The building's condition and location can influence its marketability and financing prospects.
A property with significant structural problems may require additional capital and a more detailed assessment.
Location matters because tenant demand, employment opportunities, transportation, schools, and access to services can affect rental demand.
However, even a well-located building can perform poorly if it is purchased at an excessive price or carries unsustainable financing costs.
Calculating the Potential Income From an Apartment Building
Before applying for a loan, investors should estimate the property's operating income and expenses.
Suppose an apartment building contains ten units, each rented for $1,200 per month.
If all units were occupied and all rent were collected for a full year, the potential annual rental income would be:
10 × $1,200 × 12 = $144,000.
However, actual income may be lower because of vacancies, missed payments, concessions, or other factors.
Assume the property generates $135,000 in effective annual income after accounting for these losses and has $55,000 in annual operating expenses.
The estimated net operating income would be:
$135,000 − $55,000 = $80,000.
This figure can help investors compare the property's income with the proposed loan payments.
Operating expenses may include maintenance, property management, insurance, utilities paid by the owner, and property taxes. Net operating income generally excludes mortgage payments and certain other costs, so investors should use a consistent calculation method.
The property should also be evaluated under less favorable assumptions. Higher expenses or lower occupancy could reduce the amount available to support the debt.
Understanding the Risks of Multifamily Real Estate Financing
Multifamily investing can offer opportunities, but it also carries risks that should be considered before borrowing money.
Vacancy and Tenant Turnover
When tenants move out, owners may lose rental income while continuing to pay insurance, taxes, maintenance costs, and loan installments.
Finding new tenants may take time, especially in areas with weak housing demand.
Investors should include realistic vacancy assumptions in their financial plans.
Unexpected Repairs
Apartment buildings contain shared systems such as plumbing, roofing, electrical equipment, heating, and cooling.
A major repair can cost more than expected and affect the property's cash flow.
Professional inspections and a maintenance reserve can help reduce the risk of financial surprises.
Interest Rate Changes
Variable-rate loans may become more expensive when interest rates rise.
Higher payments can reduce the property's cash flow and make refinancing more difficult.
Investors should understand how their loan rate can change and assess whether the investment remains affordable under different rate scenarios.
Changes in Property Values
Apartment prices may decline because of economic conditions, reduced rental demand, rising financing costs, or changes in the local housing market.
Investors who need to sell during a downturn may receive less than they expected.
A long-term investment plan should not depend entirely on future appreciation.
Overestimating Rental Income
A common mistake is calculating returns using the highest possible rent while ignoring vacancies, operating costs, and tenant turnover.
Investors should base their estimates on reliable local information and verify the building's existing financial records.
Conservative assumptions can help reveal whether the property is financially sustainable.
Strategies for Improving Multifamily Investment Performance
After purchasing an apartment property, investors may identify ways to improve its financial performance.
One approach is to maintain the building properly. Prompt repairs and clean shared areas can help protect the property's condition and improve the tenant experience.
Another approach is to review operating expenses. Investors may compare insurance quotes, improve maintenance planning, or identify wasteful utility use where practical.
Professional property management can also help with tenant communication, rent collection, record keeping, and lease administration.
Renovations may improve the appeal of older units, but the expected benefits should be compared with the total cost. Improvements do not automatically justify higher rents, and local laws may limit rent increases.
The aim should be to operate the property efficiently while providing safe, well-maintained housing.
Tips for First-Time Multifamily Investors
First-time investors can take several practical steps before purchasing an apartment building.
Start with a manageable property. A smaller building may be easier to understand and manage than a large apartment complex.
Research the local rental market. Compare similar properties, asking rents, vacancy levels, and tenant demand.
Review every expense. Include repairs, insurance, taxes, management fees, utilities, and reserves in your calculations.
Compare financing options. Review interest rates, fees, repayment schedules, collateral requirements, and prepayment conditions.
Complete due diligence. Check leases, building condition, title records, zoning, and other relevant documents before closing.
Keep emergency funds available. Do not use all your available capital for the down payment and closing costs.
Seek qualified advice. Financial, legal, tax, and property professionals can help identify issues that may not be obvious to a new investor.
These steps cannot remove every risk, but they can help investors make better-informed decisions.
Final Thoughts
Multifamily real estate financing can help investors purchase apartment buildings, renovate existing properties, and expand their rental portfolios. Available funding options may include conventional residential mortgages, commercial multifamily loans, portfolio loans, bridge financing, private lending, and equity partnerships.
Each option has different eligibility requirements, costs, and risks. The right choice depends on the property's size, expected rental income, the investor's financial position, and the long-term investment strategy.
Before purchasing a multifamily property, investors should review its income and expenses, understand the proposed loan terms, complete due diligence, and prepare for vacancies and unexpected repairs.
A careful approach to financing and property management can provide a stronger foundation for responsible multifamily investing.
Disclaimer: This article is for general educational and informational purposes only. It is not financial, legal, tax, or investment advice. Financing rules and loan requirements vary by location and lender. Consult qualified professionals before making investment decisions.
Visit: https://wellrogo.com/en/
Invest in Luxury
Access curated opportunities across luxury assets, private markets, and alternative investments designed for long-term value creation and portfolio diversification.
Explore Opportunities
Private Cannabis Investing
The global cannabis market is expected to grow rapidly in the coming years. With this growth, investing with TheSeattleCannabis can be a smart move for those looking to diversify their portfolio. .
View Opportunities Dutch
 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek