 Seenclassified
 Request Access
Understanding Loan-to-Value Ratios and Risk in Real Estate Lending
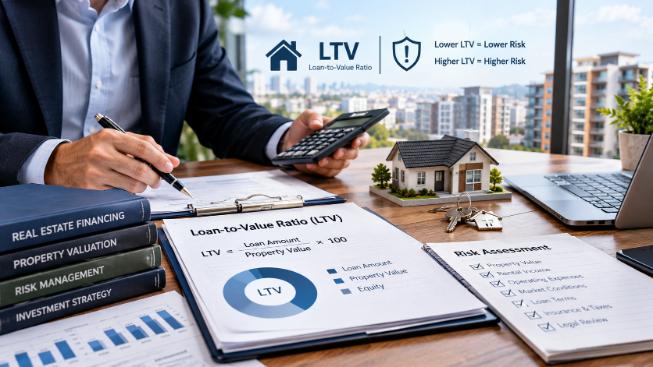
Real estate investing often requires more money than an investor can comfortably pay from personal savings. Buying a rental house, purchasing an apartment building, or developing a commercial property may require financing from a bank or another lender. Before approving a loan, lenders need to understand how much money they are lending compared with the value of the property.
One of the most important tools used for this purpose is the loan-to-value ratio, also known as LTV.
The loan-to-value ratio helps explain how much of a property's value is financed through borrowing. It also helps lenders evaluate their potential risk if a borrower cannot repay the loan. For investors, understanding LTV can make it easier to compare financing offers, estimate the required down payment, and decide how much debt a property can reasonably support.
However, LTV is not just a number used by banks. It can also help property owners understand their equity, evaluate refinancing opportunities, and prepare for changes in property values.
In this article, we will explain how loan-to-value ratios work, how lenders use them, what can make a real estate loan risky, and how investors can use this information to make better financial decisions.
What Does Loan-to-Value Mean in Real Estate?
Loan-to-value measures the size of a loan compared with the value of the property securing it.
In simple terms, it shows what percentage of a property's value a lender is financing.
For example, imagine an investor wants to purchase a rental property valued at $250,000. The investor has saved $50,000 and wants to borrow the remaining $200,000.
In this situation, the lender would finance 80% of the property's value. The investor would contribute the remaining 20%, assuming there are no other secured debts or additional costs included in the calculation.
The LTV ratio is therefore 80%.
This ratio is important because the lender is taking on more exposure when it finances a larger share of a property's value. If the borrower stops making payments and the property must be sold, the lender may have less protection against a decline in the property's price.
LTV is commonly used in residential mortgages, rental property financing, commercial real estate loans, and some property refinancing arrangements.
The acceptable ratio depends on the lender, the borrower's financial position, the type of property, and the purpose of the loan.
How to Calculate the Loan-to-Value Ratio
Calculating LTV requires two figures: the loan amount and the property value accepted by the lender.
The standard formula is:
LTV = (Loan Amount ÷ Property Value) × 100
Let's look at a practical example.
Suppose a property has a lender-accepted value of $400,000. An investor applies for a loan of $300,000.
Using the formula:
LTV = ($300,000 ÷ $400,000) × 100
LTV = 75%
This means the loan represents 75% of the property's accepted value.
The difference between the property value and the loan amount is $100,000. If there are no other secured debts, this represents the initial equity position based on that valuation.
Investors should remember that the lender may use an independent appraisal or another valuation method rather than simply accepting the purchase price. This is especially important when the seller's asking price appears higher than comparable market values.
Understanding Different LTV Levels
LTV ratios can vary significantly from one real estate investment to another. A lower ratio generally means the borrower has more equity in the property, while a higher ratio means the loan represents a larger share of its value.
Consider a property worth $500,000.
| Loan amount | LTV ratio | Borrower's equity before other costs |
|---|---|---|
| $150,000 | 30% | $350,000 |
| $250,000 | 50% | $250,000 |
| $350,000 | 70% | $150,000 |
| $400,000 | 80% | $100,000 |
| $450,000 | 90% | $50,000 |
The examples show that borrowing more money reduces the initial equity cushion.
A 50% LTV loan leaves a larger difference between the debt and property value than a 90% LTV loan. As a result, the lender may have more protection if the property's market value falls.
However, lower LTV does not automatically mean an investment is profitable. An investor can still lose money if the property has weak rental demand, high operating costs, expensive repairs, or legal problems.
LTV should therefore be considered alongside other financial and property-related information.
Why Lenders Pay Close Attention to LTV
When a lender approves a real estate loan, it takes the risk that the borrower may not repay the money as agreed.
The property often serves as collateral for the loan. If the borrower defaults, the lender may have the legal right to enforce its security and recover the outstanding debt through the property, subject to the loan agreement and applicable law.
A property sale does not always recover the entire amount owed. The market may decline, selling expenses may be high, or the property may require repairs before it can be sold.
LTV helps lenders estimate how much protection the property's value may provide.
For example, lending $200,000 against a property worth $400,000 creates a different level of collateral exposure than lending $360,000 against the same property.
The first loan has a 50% LTV, while the second has a 90% LTV.
If both properties later lose value, the second lender is more likely to face a situation in which the outstanding loan is close to or greater than the property's value.
This is one reason lenders may set maximum LTV limits for different types of real estate financing.
How Property Values Affect LTV Risk
Property values do not always move in the direction investors expect. Changes in interest rates, local employment, housing demand, and economic conditions can influence market prices.
A decline in property value can increase LTV even when the borrower has not taken out another loan.
Imagine an investor purchases a property for $300,000 with a loan of $240,000.
The initial LTV is 80%.
Now suppose the property's market value falls to $260,000 while the outstanding loan balance remains $240,000.
The new LTV is:
($240,000 ÷ $260,000) × 100 = approximately 92.3%
The investor's equity has fallen from $60,000 to $20,000, ignoring transaction costs and any other changes.
The borrower still owes the same amount, but the property's reduced value leaves less equity available.
If the value falls further, the outstanding debt may become greater than the property value. This situation is commonly known as negative equity.
Negative equity can make selling or refinancing more difficult because the sale proceeds may not be enough to repay the full loan and associated costs.
Investors should not assume that property prices will always increase. A realistic financing plan should account for the possibility of falling values.
The Difference Between LTV and a Down Payment
LTV and down payment are closely related, but they describe different parts of a property transaction.
The down payment is the amount the buyer contributes toward the purchase price from their own funds or other permitted sources.
LTV measures the loan amount against the property value accepted for lending purposes.
In a straightforward purchase where the accepted property value equals the purchase price, the down payment percentage and the difference between 100% and LTV may match.
For example, if a buyer purchases a property for $400,000 and contributes $80,000, the loan amount is $320,000. The LTV is 80%, and the down payment is 20% of the purchase price.
However, the two figures may differ when the lender's valuation is lower than the agreed purchase price or when other financing arrangements are involved.
Suppose a buyer agrees to pay $400,000 for a property, but the lender values it at $360,000. If the lender calculates LTV using the lower accepted value, a $300,000 loan would represent approximately 83.3% LTV.
This could mean the buyer needs more cash than originally expected.
Before making an offer, investors should understand how the lender determines property value and calculates the maximum loan amount.
How LTV Can Affect Interest Rates and Loan Approval
Lenders may use LTV as one factor when setting loan terms.
A lower LTV can sometimes help borrowers qualify for more favorable interest rates or fees because the loan represents a smaller share of the property's value.
A higher LTV may lead to additional requirements, more expensive financing, or a lower approved loan amount.
These outcomes are not guaranteed. Lenders also evaluate credit history, income, existing debt, property condition, loan duration, and other factors.
For example, two investors may apply for financing on properties with similar values. One investor has a strong credit history, stable income, and a 60% LTV. The other requests a 90% LTV and has limited financial reserves.
The lender may view the applications differently because the borrowers have different levels of equity and financial capacity.
A borrower should not assume that a lower LTV will guarantee approval. The property and the borrower's ability to make payments remain important.
LTV in Residential and Commercial Real Estate
Although the basic calculation is the same, lenders may evaluate LTV differently depending on the property type.
Residential Investment Properties
Residential investment properties include rental houses, condominiums, and small residential buildings.
Lenders may review the property's value, rental potential, the borrower's income, credit profile, and existing mortgage obligations.
Some loans have specific requirements for investment properties that differ from loans used to purchase a primary residence.
Investors should check whether the loan terms allow the intended use of the property.
Commercial Real Estate
Commercial properties include office buildings, retail spaces, warehouses, hotels, and larger apartment complexes.
LTV remains an important measure, but commercial lenders often place considerable emphasis on the property's ability to generate income.
A commercial building may have a relatively low LTV but still present significant risk if it has high vacancy, unreliable tenants, or large maintenance requirements.
For this reason, lenders may evaluate LTV alongside net operating income, debt service coverage, lease agreements, tenant quality, and market demand.
Construction and Development Projects
Construction loans can involve additional complexity because the property's current value may differ from its expected value after completion.
A lender may assess the land value, construction budget, borrower contribution, and projected completed value under its own lending rules.
Investors should not assume that a projected future value will automatically be accepted for calculating the maximum loan amount.
Construction costs can also increase, and delays may affect the project's financial position.
A realistic funding plan should include contingency reserves and a clear strategy for repaying or refinancing the loan.
LTV vs. Loan-to-Cost Ratio
Loan-to-value is not the same as loan-to-cost.
LTV compares the loan with the property's value. Loan-to-cost, or LTC, compares the loan amount with the eligible total cost of a project.
LTC is often useful for development and construction financing.
Consider a developer who plans a project with total eligible costs of $800,000. These costs may include land, construction, professional fees, and other approved expenses.
If the lender provides $560,000, the LTC ratio is:
($560,000 ÷ $800,000) × 100 = 70%
Now suppose the completed property is expected to be worth $1 million. If the lender uses that completed value for a separate LTV calculation, the ratio would be 56%.
The two ratios are different because they use different reference amounts.
LTC helps show how much of the project cost is being financed, while LTV measures the loan relative to property value.
Investors should confirm which calculation their lender uses and what costs or valuations are eligible.
LTV vs. Debt Service Coverage Ratio
Another important measure is the debt service coverage ratio, often shortened to DSCR.
While LTV measures the loan against property value, DSCR measures the property's income against its scheduled debt payments.
The formula is:
DSCR = Net Operating Income ÷ Annual Debt Service
Suppose an apartment building generates $84,000 in annual net operating income and requires $70,000 in annual debt payments.
The DSCR is:
$84,000 ÷ $70,000 = 1.20
This means the property generates $1.20 in net operating income for every $1.00 of scheduled annual debt service.
A higher DSCR generally indicates a larger income cushion for making loan payments, although lender requirements vary.
Consider two properties with the same 70% LTV. One produces stable rental income and has a DSCR above the lender's required level. The other has high vacancy and insufficient income to cover its debt.
The properties have the same LTV but different repayment risks.
This illustrates why investors should evaluate both property value and income before taking on debt.
The Risks of Borrowing Too Much Against a Property
High LTV financing can allow investors to purchase properties with less initial cash. However, borrowing a large amount also creates several potential risks.
Reduced Equity
A borrower who contributes a small down payment begins with a smaller equity cushion. If the property value declines, that cushion can disappear quickly.
Higher Financing Costs
Depending on the lender, a higher LTV may result in higher interest rates, additional fees, or other loan conditions.
These costs can reduce the investment's cash flow.
Limited Refinancing Opportunities
An investor may plan to refinance after renovating a property or increasing rental income.
However, refinancing depends on the property's value, the outstanding debt, the borrower's finances, and the lender's current requirements.
If property values fall, the investor may not qualify for the expected replacement loan.
Cash Flow Pressure
A large loan can create substantial monthly payments.
If a rental property becomes vacant or requires an unexpected repair, the owner may struggle to meet those payments without sufficient cash reserves.
Greater Exposure to Market Changes
Property markets can be affected by interest rates, local employment, new construction, and changes in demand.
Investors using high leverage may have fewer options if market conditions deteriorate.
Borrowing should therefore be based on what the investor can reasonably afford, rather than simply taking the largest loan available.
Practical Ways to Manage LTV Risk
Investors can take several steps to manage the risks associated with real estate borrowing.
1. Choose a Suitable Loan Amount
Before applying for financing, calculate how much debt the property can reasonably support.
Consider the required payments, expected income, operating expenses, and personal financial obligations.
A loan that looks affordable under ideal conditions may become difficult to manage if expenses increase.
2. Maintain Emergency Reserves
Avoid using all available cash for the down payment.
Property owners may need money for repairs, insurance, taxes, vacancy, and other unexpected costs.
The appropriate reserve depends on the property and the investor's financial position.
3. Use Reliable Property Valuations
Compare the lender's valuation with recent sales of similar properties.
If the valuation seems unusually high or low, ask how it was determined and whether additional professional review is appropriate.
Reliable valuations help investors avoid basing their decisions on unrealistic property values.
4. Test Different Market Scenarios
Calculate how the investment might perform if property values decline, rental income falls, or interest rates increase.
For a rental property, check whether the income can still cover operating costs and debt payments under less favorable conditions.
For a development project, account for delays and possible cost overruns.
5. Compare Complete Loan Offers
Do not compare lenders based only on the maximum LTV they offer.
Review the interest rate, fees, repayment period, early repayment conditions, collateral requirements, and other contractual terms.
A smaller loan with manageable payments may be more suitable than a larger loan that leaves little room for unexpected expenses.
6. Plan for the End of the Loan
Some property loans are designed to be refinanced or repaid after a short period.
If the investment depends on refinancing, consider what could happen if the property value falls or lending conditions become stricter.
A backup repayment plan can help investors prepare for uncertainty.
A Worked Example: Choosing Between Two Financing Options
Imagine an investor is considering a rental property valued at $600,000.
Two lenders offer different loan amounts.
Option A
-
Loan amount: $360,000
-
Property value: $600,000
-
LTV: 60%
-
Initial equity based on value: $240,000
Option B
-
Loan amount: $480,000
-
Property value: $600,000
-
LTV: 80%
-
Initial equity based on value: $120,000
Option B requires less initial capital from the investor, assuming the property value and other costs remain the same. However, it also creates a larger debt obligation.
Option A provides a bigger equity cushion and may result in lower payments, depending on the loan terms. The investor must nevertheless consider whether committing an additional $120,000 to the property leaves enough cash for other investments and unexpected costs.
To choose between the options, the investor should compare the full financing costs, projected rental income, operating expenses, and available cash reserves.
There is no single correct choice for every investor. The right option depends on the investment strategy, financial position, and ability to manage risk.
Common LTV Mistakes Real Estate Investors Should Avoid
Understanding the formula is only the first step. Investors should also avoid several common mistakes.
Assuming property values always rise: A market downturn can increase LTV even when the loan balance has not increased.
Using the asking price without verification: The lender may rely on a different valuation when deciding how much to lend.
Ignoring other secured debts: Additional borrowing against the property can affect the overall debt and equity position.
Focusing only on LTV: A low ratio does not guarantee strong rental income, manageable expenses, or a good investment.
Borrowing the maximum amount available: The largest approved loan may not be the most appropriate loan for the investor's financial situation.
Forgetting transaction costs: Legal fees, closing costs, repairs, and other expenses can increase the cash needed to complete a purchase.
Avoiding these mistakes can help investors assess financing more realistically and make decisions based on the property's complete financial picture.
Final Thoughts
The loan-to-value ratio is a useful tool for understanding how real estate financing works and how much risk a lender may face when providing a property loan.
By comparing the loan amount with the property's accepted value, LTV helps investors estimate their initial equity position and understand how changes in property prices may affect their financial situation.
However, LTV is only one part of a responsible lending decision. Property income, operating expenses, loan terms, market conditions, and the borrower's ability to repay the debt also matter.
Before funding a real estate investment, review the property valuation, calculate the LTV, compare financing options, and maintain enough cash to manage unexpected expenses.
The goal is not simply to borrow as much as possible. It is to select financing that supports the investment strategy without creating unnecessary financial pressure.
A well-planned approach to borrowing can help property investors understand their exposure, prepare for market changes, and make more informed decisions over the long term.
Disclaimer: This article is intended for educational and informational purposes only. It does not provide financial, legal, tax, or investment advice. Loan-to-value requirements and lending practices vary by lender, property type, and location. Consult qualified professionals before making real estate financing decisions.
Invest in Luxury
Access curated opportunities across luxury assets, private markets, and alternative investments designed for long-term value creation and portfolio diversification.
Explore Opportunities
Private Cannabis Investing
The global cannabis market is expected to grow rapidly in the coming years. With this growth, investing with TheSeattleCannabis can be a smart move for those looking to diversify their portfolio. .
View Opportunities Portuguese
 English
 Arabic
 French
 Spanish
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek